Roof Insurance Claim Denied in Texas? Here’s What to Do [2026]
Nearly 47% of homeowner insurance claims in Texas are closed without payment. If your roof claim was denied after a hailstorm in Roanoke or DFW, you have legal options — re-inspection, the Texas appraisal clause, and TDI complaints. A denial is not the final word.
Why Claims Get Denied
“Wear and tear” classification — adjusters call storm damage pre-existing deterioration.
Insufficient documentation — no professional inspection report = easy denial.
Cosmetic damage exclusions — some policies exclude non-functional damage.
Missed deadlines — Texas gives 1 year from storm date.
Lowball settlements — approved but underpaid.
Step 1: Get Independent Inspection
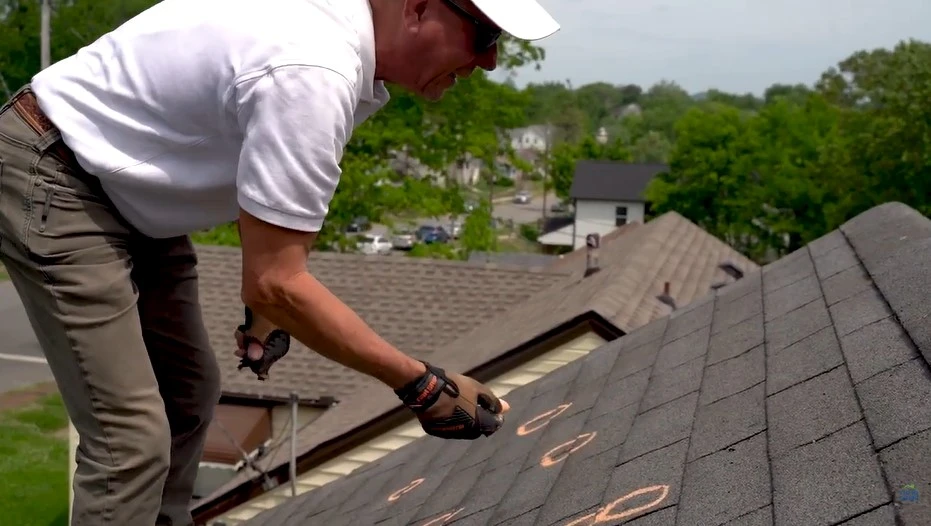
Your insurer’s adjuster works for them. An independent HAAG-certified roofer provides test-square counts, component documentation, and a report distinguishing storm damage from wear. This evidence is your foundation for appeal.
Step 2: Request Re-Inspection
Submit your independent report and request a different adjuster. We attend re-inspections to ensure every finding is seen. In Briarwyck, we reversed a denial in 18 days using this approach — while 3 neighbors had already been approved for the same storm.
Step 3: Texas Appraisal Clause
Your most powerful tool. You hire an independent appraiser, insurer hires theirs, and if they disagree, a neutral umpire decides (binding). Results often 2–3x the original offer. Faster and cheaper than litigation.
Step 4: File TDI Complaint
The Texas Department of Insurance investigates complaints. If neighbors were approved but you were denied for the same storm, TDI puts regulatory pressure on your insurer.
Your Texas Rights
✓ 1 year to file from storm date
✓ Choose your own contractor
✓ Request re-inspection
✓ Invoke appraisal clause
✓ File TDI complaint
⚠️ Illegal for any contractor to waive your deductible
Don’t Accept Denial Without a Fight
Free inspection + documentation + claim support.
Get Help (737) 738-8111